Ciro Csa Canadian Investment Dealers
CIPF CAD $1M Coverage Rules: CIRO General vs. Separate Registered Filings
Under the CIPF Coverage Policy for CIRO (formerly IIROC and MFDA) broker-dealers, Canadian investors receive CAD $1,000,000 for all General Accounts combined—including TFSA and FHSA!—plus separate CAD $1,000,000 pools for RRSP/RRIF and RESP regulatory filings.
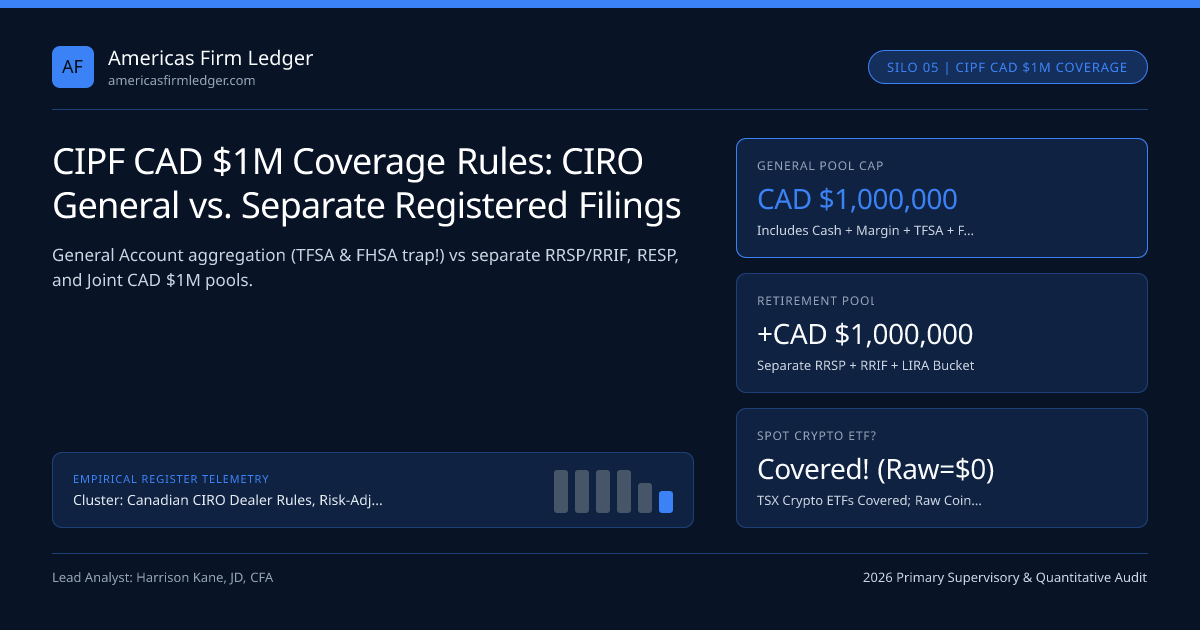
Ask ten affluent Canadian investors whether their TFSA (Tax-Free Savings Account) or FHSA (First Home Savings Account) gets its own standalone CAD $1,000,000 insurance bucket at a CIRO brokerage firm, and nine of them will guess "yes—it's a registered plan!" Nine out of ten are wrong! Under the official CIPF Coverage Policy administered by the Canadian Investor Protection Fund, TFSAs and FHSAs are aggregated inside your General Account pool alongside your individual cash and margin accounts—whereas RRSPs/RRIFs/LIRAs and RESPs each receive their own separate CAD $1,000,000 coverage pool!
Master this account-grouping matrix alongside our Canadian CIRO Dealer Rules & CIPF Filing Guide inside the Canadian CIRO & CSA Topic Hub.
The Exact CIPF Account Aggregation Matrix After the CIRO / IPC Amalgamation#
On January 1, 2023, concurrent with the merger of IIROC and the MFDA into CIRO, the former IIROC CIPF and the MFDA Investor Protection Corporation (IPC) amalgamated into a single unified CIPF maintaining two segregated industry funds (the Investment Dealer Fund and the Mutual Fund Dealer Fund). For any individual investor holding accounts at a single CIRO member dealer, CIPF covers missing property (securities + cash + segregated futures collateral) up to CAD $1,000,000 per separate category:
- Pool 1 — All "General Accounts" Combined (CAD $1,000,000 Total): Combines Cash accounts, Margin accounts, Short accounts, TFSAs, FHSAs, and RDSPs held in your individual capacity at that dealer! Opening five cash accounts plus a TFSA and an FHSA at the same firm still gives one combined CAD $1,000,000 General Pool!
- Pool 2 — Registered Retirement Accounts Combined (Separate CAD $1,000,000): Combines RRSP, RRIF, LIRA, LIF, and LRIF accounts held at that dealer into a standalone CAD $1,000,000 Retirement Pool!
- Pool 3 — Registered Education Savings Plans (Separate CAD $1,000,000): Grants an additional standalone CAD $1,000,000 pool for RESPs where the client is the subscriber!
- Separate Legal Capacities (Separate CAD $1,000,000 Each): A Joint Account with a spouse (treated as one joint relationship), a formal Trust / Estate, a Corporation, or a Partnership each constitutes a separate customer capacity receiving its own CAD $1,000,000 General Pool!
Comparing CIPF vs. U.S. SIPC: Two Giant Pro-Investor Differences!#
Cross-border wealth managers advising dual U.S.-Canadian families between CIPF and U.S. SIPC must highlight two dramatic pro-Canadian differences—plus one critical exclusion:
| Protection Dimension | Canadian CIPF (CIRO Member Dealers) | U.S. SIPC (SEC/FINRA Member BDs) | Quebec MFD Exception (FISF / AMF) |
|---|---|---|---|
| Headline Per-Pool Cap | CAD $1,000,000 Per Separate Pool | USD $500,000 Per Separate Capacity | CAD $200,000 Per Fraud Claim (Quebec MFD) |
| Uninvested Cash Sub-Limit | NONE — Full CAD $1,000,000 Covers Cash! | Strict USD $250,000 Cash Sub-Cap! | Subject to Provincial MFD Scope |
| Listed Futures & Options? | COVERED Inside General Pool! | Futures EXCLUDED ($0 SIPC — CFTC 4d Only!) | Investment Dealers Covered by CIPF |
| TFSA / Roth IRA Treatment | TFSA & FHSA Combined in General Pool! | Roth IRA & Traditional IRA Separate ($500k Ea) | RRSP/RRIF Separate Under CIPF |
| Crypto Assets & CFDs? | EXCLUDED ($0.00 CIPF Coverage!) | Unregistered Crypto / CFDs Excluded ($0) | Crypto Excluded Across Canada (CSA) |
Worked Calculation: Auditing a CAD $3,450,000 Family Portfolio in a BIA Part XII Failure#
Suppose Dr. Patel holds four accounts in her own name plus one joint cash account with her spouse at a CIRO investment dealer that fails with a 20% Customer Pool shortfall after rogue operational fraud (meaning BIA Part XII distributes 80% of missing property first, and CIPF covers the remaining 20% missing shortfall up to CAD $1,000,000 per pool):
- Individual Margin Account: CAD $1,100,000 net equity
- Individual TFSA: CAD $180,000
- Individual FHSA: CAD $40,000
- Individual RRSP + LIRA: CAD $1,450,000
- Joint Spousal Cash Account: CAD $680,000
- 1. General Account Pool (Margin $1.10M + TFSA $0.18M + FHSA $0.04M) = CAD $1,320,000
- 80% BIA Part XII Customer Pool Distribution = CAD $1,056,000
- Remaining Missing Property Shortfall (20% x $1,320,000) = CAD $264,000
- Compare Shortfall ($264,000) vs CIPF Pool Cap (CAD $1,000,000) -> 100% COVERED!
- 2. Retirement Pool (RRSP + LIRA Combined) = CAD $1,450,000
- 80% BIA Part XII Customer Pool Distribution = CAD $1,160,000
- Remaining Missing Property Shortfall (20% x $1,450,000) = CAD $290,000
- Compare Shortfall ($290,000) vs CIPF Pool Cap (CAD $1,000,000) -> 100% COVERED!
- 3. Joint Spousal Capacity Pool (Joint Cash Account) = CAD $680,000
- 20% Shortfall ($136,000) <= Separate Joint CIPF Cap ($1,000,000) -> 100% COVERED!
- =====================================================================================
- Total Portfolio Restored Across BIA Part XII + CIPF = CAD $3,450,000 (100%!)
Stacking Legal CIPF Coverage Pools at One CIRO Dealer#
Notice the crucial insolvency mechanic: CIPF's CAD $1,000,000 cap applies to the net missing shortfall AFTER your pro-rata share of the BIA Part XII Customer Pool Fund is distributed—not as a ceiling on gross account size! Even if 0% of assets survived in a total custodial wipeout, Dr. Patel would recover CAD $1,000,000 on her General Pool + CAD $1,000,000 on her Retirement Pool + CAD $680,000 on her Joint Account = CAD $2,680,000 directly from CIPF!
What CIPF Explicitly Excludes: Crypto Assets, Market Losses & Non-Member Affiliates#
Before wiring seven figures into a Canadian financial platform, verify against CIPF vs. CDIC deposit insurance boundaries and CSA SN 21-332 crypto platform rules: CIPF explicitly excludes crypto assets, crypto contracts, precious metal bullion certificates not held as securities, and shares lent out under Fully Paid Securities Lending! Even when a Canadian crypto platform registers as a Restricted CIRO Investment Dealer, your Bitcoin, Ether, and USDC carry CAD $0.00 in CIPF coverage!
Frequently asked questions
Why are TFSAs and FHSAs grouped inside the General Account pool instead of the Registered Retirement pool?
Under the CIPF Coverage Policy, only specific tax-deferred retirement plans (RRSP, RRIF, LIRA, LIF) and education plans (RESP) are designated as Separate Accounts by trust/tax structure; TFSAs, FHSAs, and RDSPs are legally classified as General Accounts combined with your cash and margin balances!
Does CIPF cover commodity futures and options accounts held at a Canadian CIRO investment dealer?
Yes! Unlike U.S. SIPC—which strictly excludes commodity futures—CIPF covers cash and open futures equity held in commodity futures accounts at a CIRO member investment dealer, aggregated inside the clients General Account CAD $1,000,000 pool!
If my Canadian crypto exchange became a CIRO member in 2024–2026, does CIPF now insure my Bitcoin?
No! CIPF explicitly amended and clarified its Coverage Policy so that crypto assets, digital tokens, and crypto contracts are excluded property ($0.00 coverage), even when held at a CIRO-member Restricted Dealer or Investment Dealer! However, Canadian ETFs holding Bitcoin (like TSX spot BTC ETFs) ARE securities and ARE covered by CIPF!
Are Mutual Fund Dealers in Quebec covered by CIPF?
Investment Dealers operating in Quebec ARE covered by CIPF up to CAD $1,000,000 per pool. However, Mutual Fund Dealers in Quebec remain subject to Quebec AMF and Fonds d indemnisation des services financiers (FISF) transition rules rather than the Mutual Fund Dealer Fund of CIPF for Quebec-only MFD activities.
Publication record
- Published
- November 13, 2026
- Updated
- November 15, 2026
- Author
- Harrison Kane, JD, CFA
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Harrison Kane, JD, CFA. (2026, November 16). CIPF CAD $1M Coverage Rules: CIRO General vs. Separate Registered Filings. Americas Firm Ledger. https://americasfirmledger.com/filings/cipf-1-million-cad-general-vs-separate-account-coverage-rulesRelated Ciro Csa Canadian Investment Dealers & Institutional Briefings
Explore Ciro Csa Canadian Investment Dealers Hub (20) →Ciro Csa Canadian Investment Dealers
Canadian CIRO (IIROC) Dealer Rules, Form 1 RAC & CIPF Regulatory Filings GuideCiro Csa Canadian Investment Dealers
CIPF vs. CDIC CAD $100k Deposit Insurance: Chartered Bank GIC & Cash ETF FilingsCiro Csa Canadian Investment Dealers
CSA National Instrument 31-103 Categories: CIRO Dealer & Asset Manager FilingsCiro Csa Canadian Investment Dealers
CSA NRD Filings: Form 33-109F4, MI 11-102 Passport & CIRO Broker-Dealer RegistryCiro Csa Canadian Investment Dealers
CSA Client Focused Reforms (CFR): CIRO Know-Your-Product & Conflict FilingsCiro Csa Canadian Investment Dealers
CRM2 & 2026 CRM3 Total Cost Reporting: CIRO & CSA Fee Regulatory FilingsCiro Csa Canadian Investment Dealers
CIRO (IIROC) OTC Derivatives, CFD & Retail Forex Margin Regulatory FilingsCiro Csa Canadian Investment Dealers
Quebec AMF Derivatives Act & CSA MI 91-102 Binary Ban: CIRO Regulatory FilingsRegulatory Compliance
US SEC enforcement activity plunges two years into Trump administration - ReutersMarket Insights
CoreWeave's Funding Challenges Are 'Manageable:' Bank of America Sees the Stock More Than Doubling From Here - BenzingaMarket Insights
Nasdaq futures rise over 500 points: 5 things to know before Wall Street opens - InvezzMarket Insights
Nasdaq Futures forecast: AI stocks rebound as Goldman Sachs, JPMorgan and Morgan Stanley assess market outlook - Beinsure
Americas Firm Ledger Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.