Finra Brokercheck Form Bd Crs Filings
FINRA Rule 1017 Continuing Membership Application (CMA): 25% Ownership & Safe Harbors
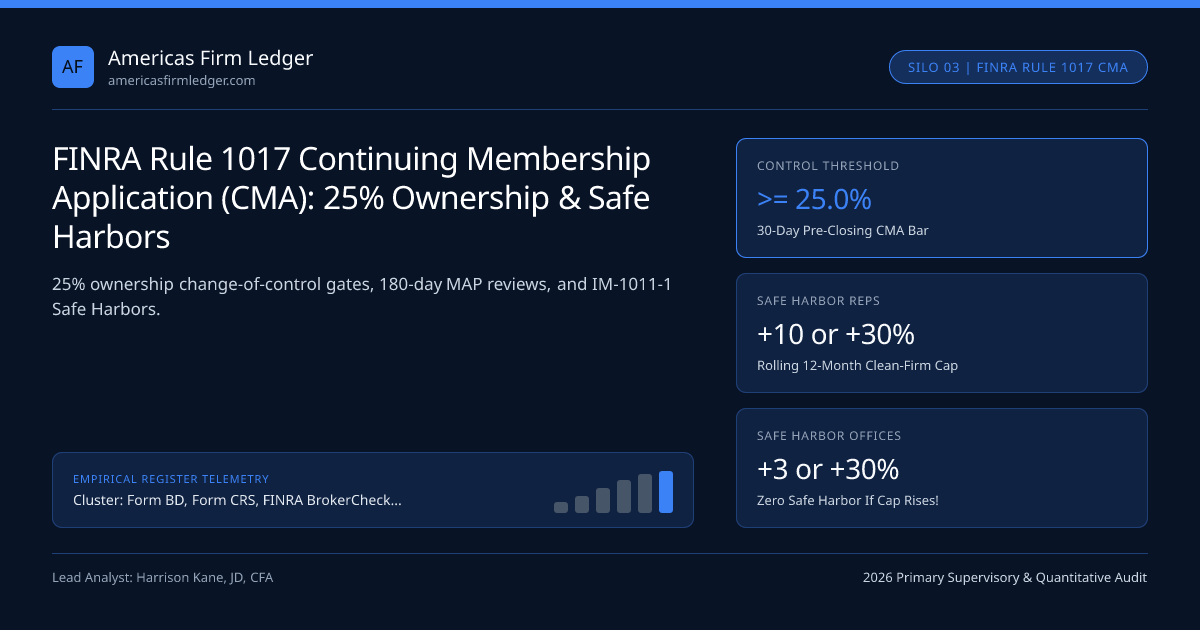
FINRA Rule 1017 requires member broker-dealers to file a Continuing Membership Application (CMA) before closing mergers, 25%+ direct or indirect ownership transfers, or material business expansions—unless covered by FINRA IM-1011-1 Safe Harbor expansion limits.
In technology M&A, startups routinely acquire shell companies on Friday afternoon and rebrand them on Monday morning. Attempt that with a U.S. broker-dealer ("buying a clean FINRA shell and closing before regulatory approval") and FINRA's Membership Application Program (MAP) can impose interim operational restrictions, order immediate rescission, or expel the firm! Under FINRA Rule 1017, five categories of ownership changes, asset transfers, and material changes in business operations require formal MAP scrutiny across a 180-calendar-day statutory review clock!
This M&A and business-expansion manual builds directly on Form BD Schedules A, B & C ownership brackets inside our Form BD, Form CRS & BrokerCheck institutional guide, contrasting expansion gates with Form BDW 60-day broker-dealer withdrawals.
Five Events Triggering a Mandatory FINRA Rule 1017 CMA#
Under FINRA Rule 1017(a)(1)–(5), a FINRA member must file a digital CMA via FINRA Firm Gateway for approval of:
- Mergers (a)(1) or Direct/Indirect Acquisitions (a)(2) by or with another broker-dealer;
- Asset Dispositions (a)(3) transferring 25% or more of the member's assets or any asset/business line generating 25% or more of the member's earnings measured on a rolling 36-month basis;
- 25% Ownership or Control Changes (a)(4): A change in the equity ownership or partnership capital of the member (direct OR indirect up the Schedule B chain!) that results in one person or entity directly or indirectly owning or controlling 25% or more of the equity or partnership capital (Critical Timing Rule: For (a)(4) ownership changes without a material business change, the CMA must be filed at least 30 calendar days PRIOR to effecting the change—allowing closing after 30 days unless FINRA imposes interim restrictions, though buyers almost always make Final FINRA CMA Approval a contractual M&A closing condition!);
- Material Change in Business Operations (a)(5): Removing/modifying a Membership Agreement restriction, adding market making, becoming an underwriter, adding digital-asset / ATS business, increasing minimum Net Capital requirements (e.g., jumping from $5k introducing to $250k carrying!), or exceeding IM-1011-1 Safe Harbor headcount/branch expansion caps (Cannot be implemented until FINRA issues written approval!); and
- Rule 1017(a)(6)–(7) Disqualifying Arbitrations / MAP Materiality Consultations ("MatCon"): Under IM-1011-2, firms with unpaid awards or specified pending arbitration/disciplinary claims face mandatory Materiality Consultations before ownership transfers or expansions!
The FINRA IM-1011-1 "Safe Harbor for Business Expansions" Matrix!#
How fast can a broker-dealer hire Series 7 reps, open suburban branches, or add market-making stocks without triggering a 6-month CMA freeze? FINRA Interpretive Material 1011-1 grants an automatic rolling 12-month Safe Harbor (available only if neither the firm nor its control affiliates have a stipulated disciplinary history in the past 5 years!):
| Expansion Category (Rolling 12-Month Measurement) | Current Size of FINRA Member | Safe Harbor Expansion Limit (No CMA Needed!) | Exceeding Cap Triggers |
|---|---|---|---|
| Associated Persons Involved in Sales | 1 – 10 Reps | +10 Reps in a rolling 12-month period | Mandatory Rule 1017 CMA (or MatCon) |
| Associated Persons Involved in Sales | 11 or More Reps | +10 Reps OR +30% Increase (Whichever is Greater!) | Mandatory Rule 1017 CMA |
| Offices (OSJs + Registered/Unregistered Branches) | 1 – 5 Offices | +3 Offices in a rolling 12-month period | Mandatory Rule 1017 CMA |
| Offices (OSJs + Registered/Unregistered Branches) | 6 or More Offices | +3 Offices OR +30% Increase (Whichever is Greater!) | Mandatory Rule 1017 CMA |
| Number of Markets Made | 1 – 10 Markets | +10 Markets in a rolling 12-month period | Mandatory Rule 1017 CMA |
| Number of Markets Made | 11 or More Markets | +10 Markets OR +30% Increase (Whichever is Greater!) | Mandatory Rule 1017 CMA |
| Increase in Minimum Net Capital Floor | Any Firm ($5k -> $50k / $250k) | ZERO Safe Harbor! (Any Statutory Floor Increase!) | Mandatory Rule 1017 CMA! |
Quantitative 24.9% Staged Acquisition & Safe-Harbor Headcount Formula#
In fintech broker-dealer acquisitions, buyers needing immediate commercial integration often structure a Two-Tranche Signing/Closing: acquiring 24.9% voting & economic equity at Signing (Tranche 1 — Zero Board Control!), filing the Rule 1017 CMA the same week, and closing the remaining 75.1% (Tranche 2) upon written FINRA MAP approval! Meanwhile, growing wealth firms track IM-1011-1 headcount math daily:
- PermittedPeakRepHeadcount = LowestRepCountInPrior12m + MaxSafeHarborNewReps_12m
- Worked IM-1011-1 Safe Harbor Expansion Audit (Regional Wealth Broker-Dealer, Clean 5-Yr Record):
- Lowest Registered Sales Rep Count over trailing 365 days = 40 Reps (measured from rolling 12-month trough!)
- Safe Harbor Allowance = max(10, floor(0.30 * 40)) = max(10, 12) = +12 Net Additional Sales Reps!
- Maximum Permitted Headcount Without Filing a CMA = 40 + 12 = 52 Sales Reps!
- Trap: Recruiting a 14-advisor breakaway team tomorrow (jumping from 40 to 54 reps) breaches Safe Harbor by 2 reps -> Must file MatCon/CMA BEFORE onboarding Rep #53!
Top FINRA MAP Scrutiny Gates in Fintech & Crypto CMAs#
Why "Buying a Dormant $5,000 Broker-Dealer Shell" Rarely Saves Time Over an NMA!#
Venture founders routinely pay $200,000+ for a dormant 1990s mutual-fund broker-dealer thinking they will launch a mobile options app in 30 days. Reality check: changing a dormant (k)(1) mutual-fund shell into a (k)(2)(ii) mobile retail equities/options platform triggers BOTH a Rule 1017(a)(4) 100% ownership change AND a Rule 1017(a)(5) material business change—subjecting the buyer to all 14 FINRA Rule 1014 Admission Standards (virtually identical to a fresh 180-day New Membership Application, plus inheriting 25 years of the shell's hidden arbitration liabilities!). Conversely, when shutting down an unused broker-dealer cleanly, examine SEC & FINRA Form BDW 60-day withdrawal rules inside the Form BD, BrokerCheck & CAT Topic Hub.
Frequently asked questions
Can an acquirer buy 24.9% of a broker-dealer today without waiting for FINRA Rule 1017 CMA approval?
Yes, provided the 24.9% stake carries zero contractual negative-control vetoes over day-to-day management and zero options exercisable within 60 days that push deemed ownership to 25% or more! The firm then files a Form BD Schedule A/C amendment within 30 days and submits the CMA before closing the remaining 75.1%.
What is a FINRA Materiality Consultation ("MatCon") and when should we use it instead of a full CMA?
When a proposed new product or expansion sits in a gray area (neither clearly inside IM-1011-1 Safe Harbor nor clearly triggering a Net Capital jump), filing a voluntary MatCon lets FINRA MAP determine—often in 30 to 45 days with zero CMA filing fee—whether a full Rule 1017 CMA is required.
How does FINRA verify "Source of Funds" during a Rule 1017 acquisition review?
Under FINRA Rule 1014(a)(3), MAP examiners trace every dollar of purchase price and capital infusion back to its original legitimate source—demanding 3 to 6 months of bank statements, audited fund financials, tax returns, and wire receipts to rule out borrowed or illicit capital.
Why is the IM-1011-1 Safe Harbor measured from the "lowest" rep count in the prior 12 months?
Measuring from the rolling 12-month trough prevents firms from gaming the 30% limit via temporary churn; if you dropped from 50 reps to 30 reps six months ago, your 30% Safe Harbor ceiling is 30 + 10 (the 10-rep minimum) = 40 reps, not 65!
Publication record
- Published
- November 13, 2026
- Updated
- November 14, 2026
- Author
- Harrison Kane, JD, CFA
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 4 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Harrison Kane, JD, CFA. (2026, November 14). FINRA Rule 1017 Continuing Membership Application (CMA): 25% Ownership & Safe Harbors. Americas Firm Ledger. https://americasfirmledger.com/filings/finra-rule-1017-continuing-membership-application-cma-25pctRelated Finra Brokercheck Form Bd Crs Filings & Institutional Briefings
Explore Finra Brokercheck Form Bd Crs Filings Hub (20) →Finra Brokercheck Form Bd Crs Filings
Form BD, Form CRS, FINRA BrokerCheck & CAT Supervision: Institutional Filing GuideFinra Brokercheck Form Bd Crs Filings
Form BDW Broker-Dealer Withdrawal: SEC Rule 15b6-1 60-Day Wind-Down & Record CustodyFinra Brokercheck Form Bd Crs Filings
SEC Form CRS Relationship Summary Audit: 2-Page vs 4-Page Caps, Prompts & Fee ConflictsFinra Brokercheck Form Bd Crs Filings
SEC Regulation Best Interest (Reg BI) Rule 15l-1: Care, RCAP Alternatives & Conflict MitigationFinra Brokercheck Form Bd Crs Filings
FINRA Form U4 Item 14 Disclosures: $5k Written Complaints, $15k Settlements & 30-Day LiensFinra Brokercheck Form Bd Crs Filings
FINRA Form U5 Termination Disclosures: 30-Day Clocks, Section 7 Reviews & Defamation ClaimsFinra Brokercheck Form Bd Crs Filings
FINRA BrokerCheck Customer Dispute Expungement: Rule 2080, Rule 12805 & Unanimous PanelsFinra Brokercheck Form Bd Crs Filings
FINRA Rule 4530 Self-Reporting Guide: 30-Day Internal Conclusions & Quarterly Complaint CodesCFTC Nfa Fcm Segregated Residual Interest
CEA Section 4d(f) & CFTC Part 22 Cleared Swaps LSOC Explained: Eliminating Fellow-Customer RiskCFTC Nfa Fcm Segregated Residual Interest
CFTC Rule 1.22 Residual Interest Target Explained: Blocking Fellow-Customer Margin UsageCFTC Nfa Fcm Segregated Residual Interest
CFTC Rule 1.25 Permitted Investments (2025 Overhaul): US Treasuries, Short-Term Treasury ETFs & CapsCFTC Nfa Fcm Segregated Residual Interest
CFTC Rule 1.17 FCM Adjusted Net Capital: $1M Floor vs 8% Customer & Non-Customer Risk Margin
Americas Firm Ledger Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.